A closer look at what the EU's new textile destruction ban actually changes — and why demand-driven production is becoming a business necessity rather than a sustainability nice-to-have.
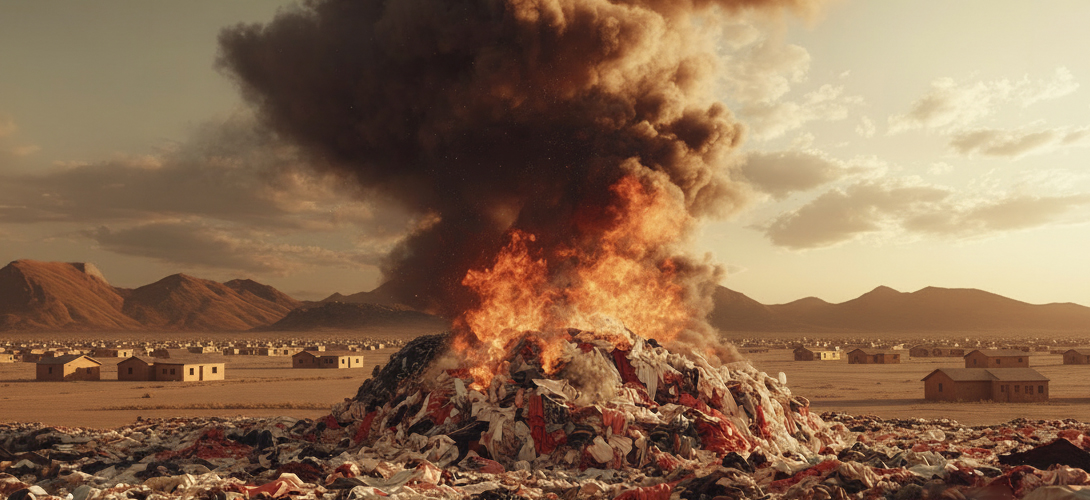
The regulation adopted on 9 February 2026 under the Ecodesign for Sustainable Products Regulation (ESPR) prohibits the destruction of unsold clothing, textile accessories, and footwear across the European Union. While this policy removes a controversial practice, it leaves the underlying engine of the fashion industry unchanged: structural overproduction.
The regulation establishes strict enforcement timelines and clear operational rules:
According to the European Commission, an estimated 4% to 9% of unsold textiles in the EU are destroyed before ever reaching a consumer.
While stopping this practice removes the most extreme waste valve, the law itself is not a ban on overproduction. Companies retain full legal standing to produce excess inventory, run steep promotional campaigns, and offload overstock through secondary markets. The core shift introduced by the ESPR is transparency. Mandatory reporting from February 2027 onward transforms internal inventory waste into public knowledge.
For many brands, the immediate operational response to the regulation appears simple: connect inventory to secondary resale platforms, expand dedicated outlet channels, or sell excess inventory in bulk to third-party discounters.
While this path maintains legal compliance, it introduces distinct long-term risks to brand equity. When excess stock continuously flows into secondary channels, brands face accelerated value depreciation and a permanent discount cycle. For luxury and premium market segments, historical destruction was driven primarily by a desire to preserve price integrity and exclusivity. With destruction banned and transparency mandated, relying heavily on outlets creates direct brand positioning conflicts.
The financial and reputational pressure created by public reporting shifts the strategic calculus. Increased scrutiny from investors and consumers turns excess inventory into a visible liability rather than an acceptable cost of doing business.
This structural shift elevates demand-driven production from an environmental ideal to an operational necessity.
From the perspective of demand-driven production platforms like ShapelyTech, technology makes it possible to align manufacturing directly with real-time customer data. By integrating digital measurement, automated pattern cutting, and direct-to-commerce workflows, brands trigger production on confirmed orders rather than speculative forecasting.